Flagship Life-Beauty Practice · Full Audit
Merger dividends showed on the surface while the operating base loosened underneath
2025.01 – 2026.06 (18 months of operating data) · Client: Flagship pure life-beauty practice of an international premium aesthetics-space chain (anonymized)
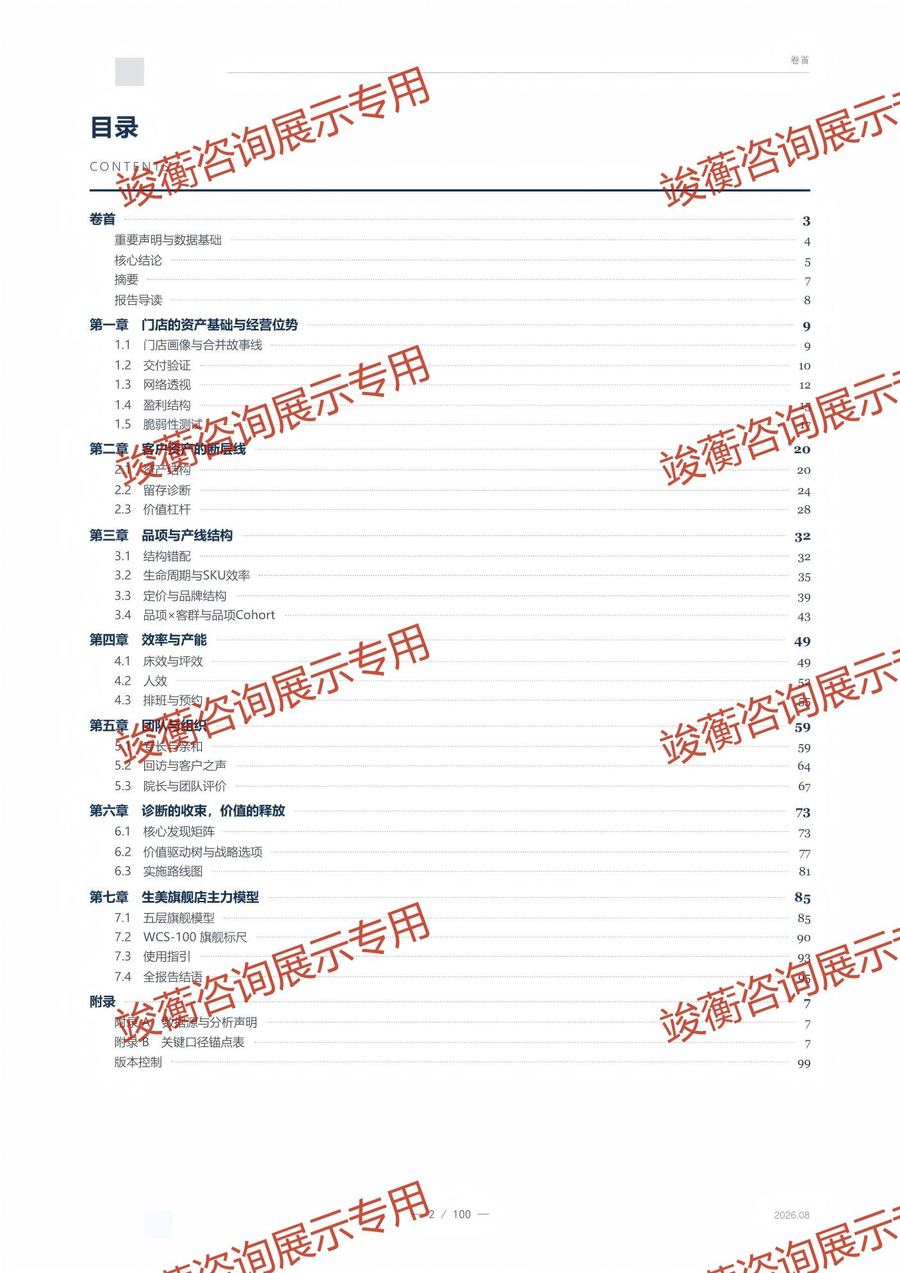
| Item | Fact | Definition / note |
|---|---|---|
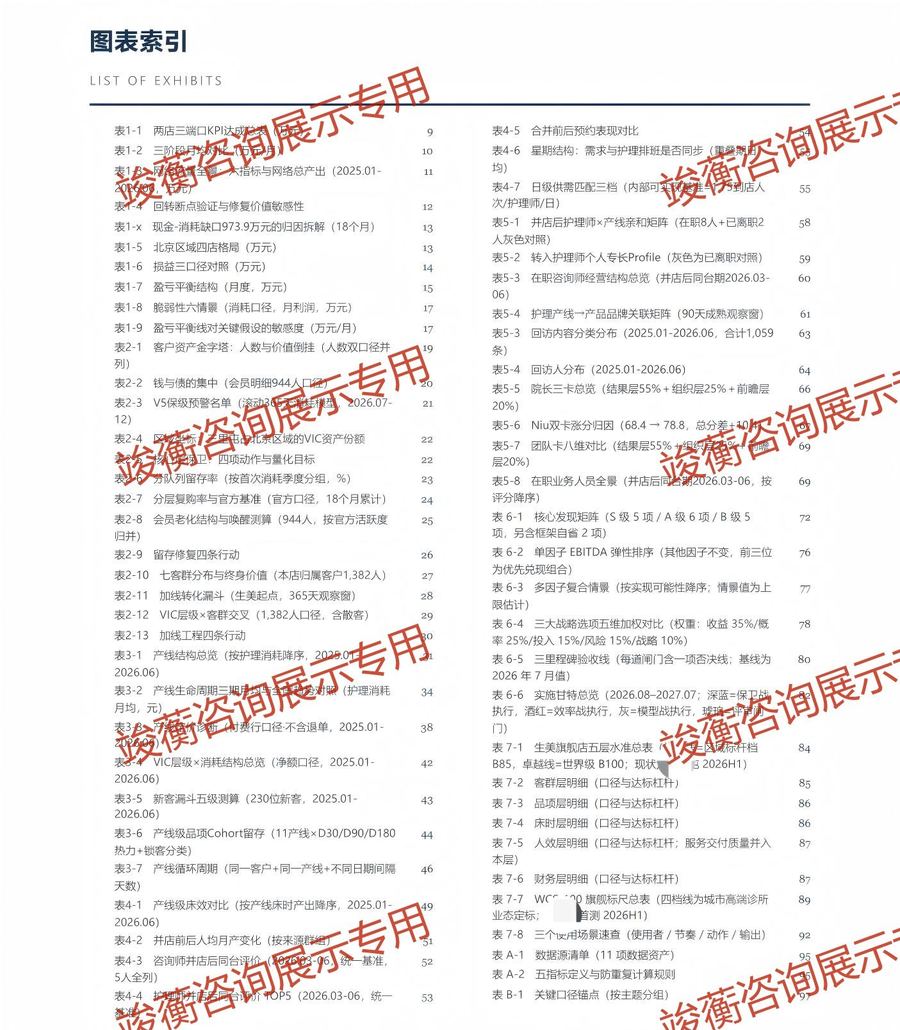
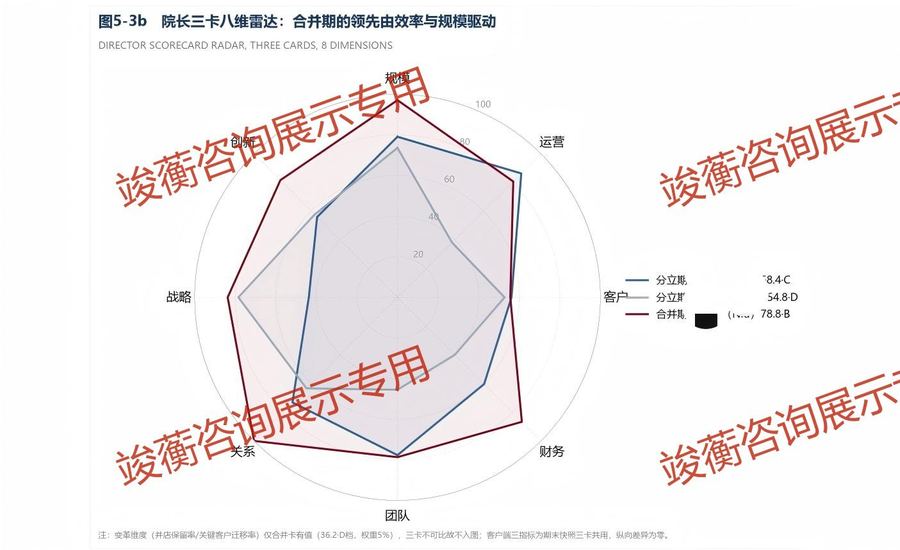
| WCI World-Class Clinic Index | 57.0 | 7 dimensions, 19 indicators recomputed on a live sheet; pass band 45–59, near the 60 promotion line |
| 18-month cash revenue | RMB 21.549M | Single life-beauty product line |
| Net delivered consumption | RMB 11.776M | Excludes product and gift offsets |
| VIC retention rate | 36.4% | Dashboard shows 56; chain-wide mean 33.2% |
| Bed utilization | 29.6% | 0-score item on the WCS-100 checkup |
| Staff retention rate | 54.8% | 0-score item on the WCS-100 checkup |
| Margin of safety | −1.2% | Break-even 319.5 visits/month vs. current 316 |
| 2026H2 cash gap | RMB 1.777M | Exceeds the four levers combined (RMB 1.456M) |
| Dormant reactivation rate | 21.3% | 64 of 301 dormant clients returned within six months |
| Chair-hour reallocation upside | RMB 188K/month | 5% of chair-hours reallocated to the highest-contribution service |
| Sep–Oct 2026 actuals | Cash 105% / 103%; consumption 94% / 101% | Pulled from CRM dashboards, as of Oct 2026 |
Full case file
Background
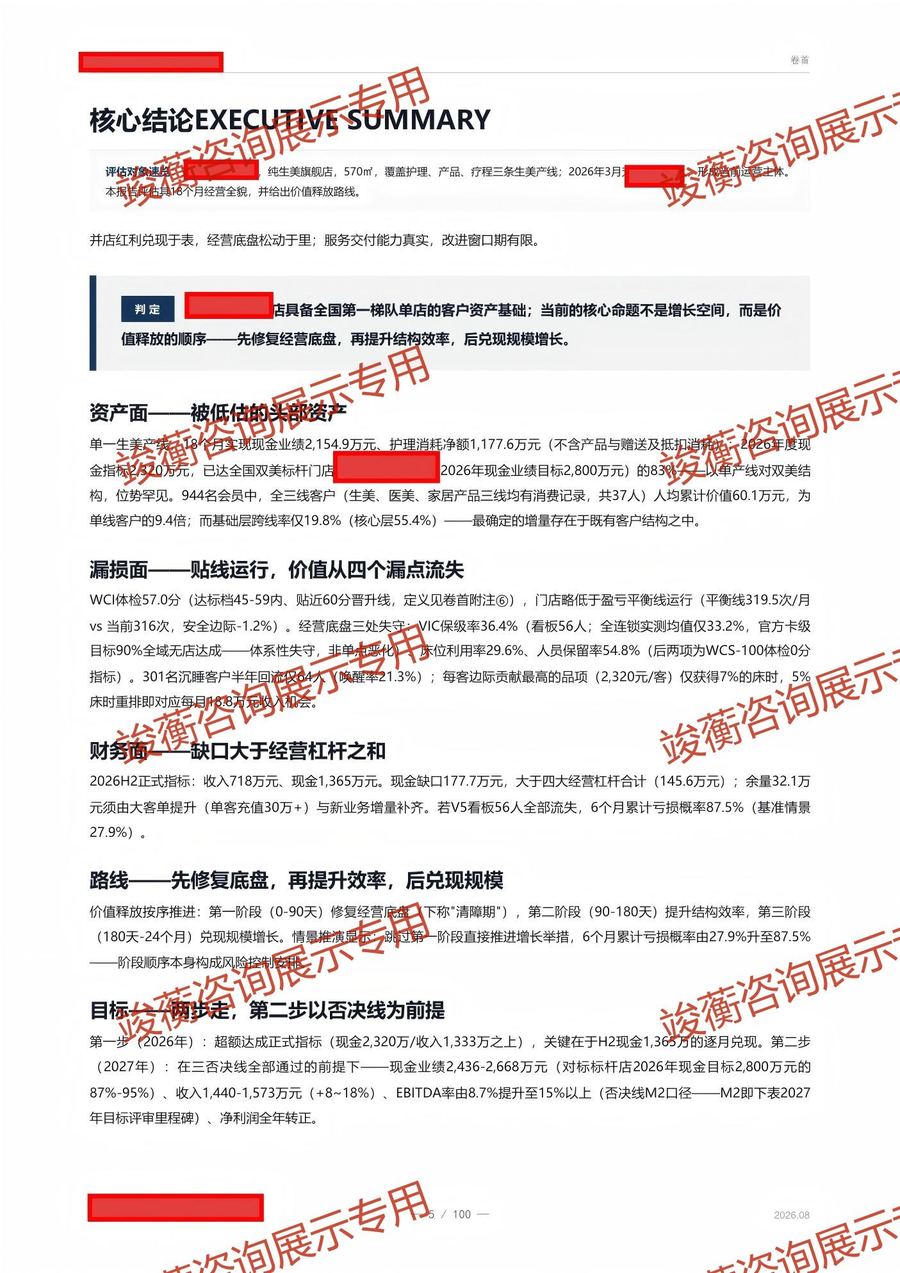
A 570 m² flagship pure life-beauty practice produced RMB 21.549M in cash revenue and RMB 11.776M in net delivered consumption over 18 months on a single life-beauty line (excluding product and gift offsets). The 2026 cash target is RMB 23.2M: 83% of the same-period target of the chain's dual-beauty benchmark store. After a same-city store merged in March 2026, scale rose while the base loosened. Commissioned by the group, I ran the full audit as product lead and chief effectiveness consultant.
Symptoms
Four conditions held at once: the flagship carries the group's heaviest cash-flow duty with high fixed costs; staff and bed efficiency are both off and the team is hard to manage; repurchase is carried by promotions; and the whole profit statement cannot be computed. The audit's core judgment in one sentence: service delivery capability is real, and the window for improvement is limited.
If one of these is yours, that is our work
- Heavy cash-flow duty on the flagship
- Profit nobody can compute
- Staff and bed efficiency off
- Repurchase sustained by promotions
- VIP retention at barely one third
Diagnosis
All 14 dimensions and 678 indicators passed through the sheet; four findings.
Assets undervalued. Of 944 members, only 37 had consumed across all three lines: life beauty, medical aesthetics, home products: at RMB 601K cumulative value per head, 9.4× a single-line client; base-tier cross-line rate 19.8%, core tier 55.4%. The most certain increment sits inside the existing client structure.
Three failures in the base. VIC retention 36.4% (chain-wide measured mean 33.2%; no store reaches the official 90% tier-target: a systemic failure); bed utilization 29.6%; staff retention 54.8%. The last two are 0-score items on the WCS-100 world-class clinic checkup.
Running on the line. Break-even 319.5 visits/month against 316 current: a −1.2% margin of safety.
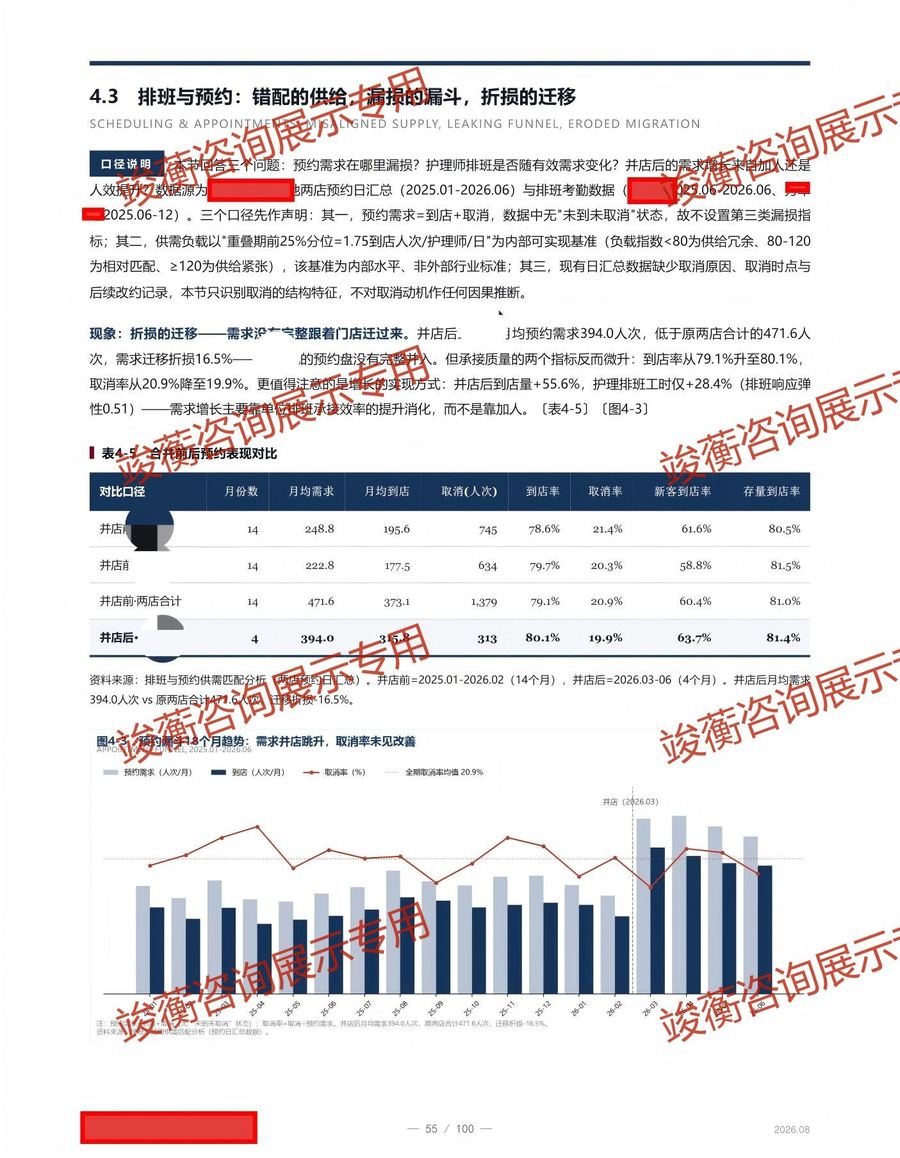
Value leaking from the holes. Of 301 dormant clients only 64 returned within six months (21.3% reactivation). The highest-contribution service (RMB 2,320/client) occupies just 7% of chair-hours; reallocating 5% corresponds to RMB 188K/month of revenue opportunity.
Actions
Set the stop-loss lines before talking growth. Three kill criteria: M1 (2026.10.31) V5 retention ≥60%; M2 (2027.01.31) EBITDA ≥15%; M3 (2027.07.31) base-tier cross-line ≥30%: missing a line triggers a program re-review; no promotion while failing.
The path runs in three segments. Days 0–90, clearing: all 56 dashboard members bound to retention targets, handover-contingency plans for key roles, dormant-client activation ownership moved from consulting to the store manager.
Days 90–180, efficiency: chair-hour reallocation and roster reform (worth RMB 188K/month) and cutting ineffective retention promotions.
After day 180, growth. Scenario modeling shows skipping the clearing phase pushes the 6-month cumulative-loss probability from 27.9% to 87.5%: the sequencing itself is risk control.
Results
- WCI World-Class Clinic Index 57.0 (7 dimensions, 19 indicators recomputed; pass band 45–59)
- 18-month cash revenue RMB 21.549M; net delivered consumption RMB 11.776M
- 2026H2 cash gap RMB 1.777M (exceeds the four levers combined at RMB 1.456M)
- Implementation actuals (through Oct 2026, CRM dashboards): Sep–Oct cash achievement 105% / 103%, consumption 94% / 101%; no kill-criterion re-review triggered
Verification
The conclusions' credibility comes from definitions, not opinions: delivered revenue is counted net of gifts and offsets; year-on-year comparisons use equal windows only; the WCS-100 score was recomputed item by item on a 7-dimension, 19-indicator live sheet. The three kill criteria are written into the report: miss the bar within the window and the model is judged not to hold for this practice.
Principal’s read · SAM Chengjun Xu
It never occurred to me that a treatment cognitively classed as ablative and damaging would be the highest chair-hour yielder: and that it converts clients into recharge more easily than our nine-year flagship traffic line.
On-site evidence